Financial and Insurance Support for RAF Brize Norton Personnel
Approx. 12 minute read
Insurance and Financial Guidance for RAF Brize Norton Personnel
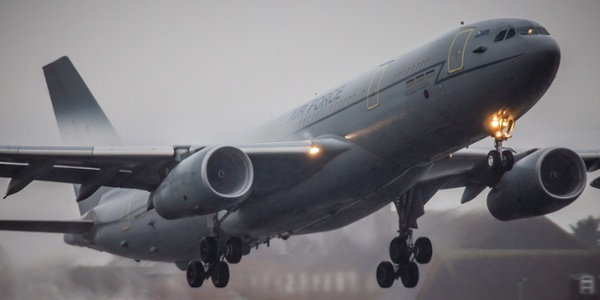
RAF Brize Norton, in Oxfordshire, is the largest RAF Station, with approximately 5,800 service personnel, 300 civilian staff, and 1,200 contractors. The station is home to the RAF’s Air Mobility Force, encompassing strategic and tactical air transport and air-to-air refuelling forces, as well as being host to many lodger and reserve units. For the thousands of personnel and their families who live in and around Carterton, Witney, and the surrounding Oxfordshire villages, the financial planning and insurance needs that come with serving life are substantial and often poorly understood.
This guide sets out the protection products available to RAF Brize Norton personnel, explains exactly what your Ministry of Defence benefits do and do not cover, and identifies the gaps that personal cover should fill. Absolute Military is FCA authorised (796907) and works exclusively with serving and veteran military personnel. Everything in this guide applies to RAF personnel at Brize Norton regardless of trade, rank, or whether you live in single living accommodation on camp or in service family accommodation in Carterton.
What Your MoD Benefits Already Provide
AFPS15 Death in Service
With effect from 1 April 2022, all serving personnel are now members of AFPS15 and all other schemes have closed. This is important: whatever scheme you joined under, your death in service benefit is now calculated under AFPS15 rules.
If you die in service, your spouse or partner will receive an immediate pension paid for life and a tax-free lump sum. The lump sum is four times your final pensionable earnings and will be paid regardless of whether you have completed at least two years of qualifying service. Your spouse, civil partner or eligible partner will receive an immediate pension, paid for life, and a tax-free lump sum amounting to four times your final pensionable earnings.
AFPS05 and AFPS15 allow members to nominate in writing to the scheme administrator one or more persons or an organisation to receive any lump sum death benefit which may be payable. If you have not completed a nomination form, the benefit follows a strict hierarchy set out in the scheme rules. Keep your nomination up to date. It takes minutes and costs nothing.
Four times gross pay is a meaningful sum. For an RAF Sergeant it can easily reach £150,000 or more. But it is not a complete financial plan. It does not cover serious illness, it does not protect your mortgage if you are medically discharged rather than killed, and it stops entirely the day you leave the service.
The Income Protection Gap
One of the most significant financial facts for any serving member of the British Armed Forces is that standard income protection insurance is not available to you. Income protection plans are only available for part-time Reservists who are not about to go on a tour of duty to an active theatre of operations or conflict, do not take part in any high-risk roles such as bomb disposal or aviation. For regular serving personnel at RAF Brize Norton, income protection is simply not on offer from mainstream insurers.
This means that if you are diagnosed with a serious illness, suffer a cardiac event, or develop cancer while serving, your financial position depends entirely on service sick pay, AFPS15 ill-health provisions, and any personal cover you have arranged. There is no standalone product that will replace your salary month by month in the way income protection does for civilian workers. That gap makes the products described below considerably more important for Brize Norton personnel than they would be in a civilian context.
Serious Illness Cover: The Most Important Product for Brize Norton Personnel
Because income protection is unavailable, Serious Illness Cover (SIC) becomes the single most important personal protection product for RAF personnel and their families. It pays a tax-free lump sum on diagnosis of a qualifying condition, allowing you to cover mortgage payments, family expenses, and the costs of treatment and recovery without relying on savings or service sick pay alone.
Absolute Military uses VitalityLife Serious Illness Cover. Vitality offers three tiers: SIC 1X covers 114 conditions with payouts between 25% and 100% of your cover amount; SIC 2X covers 143 conditions with payouts between 15% and 100% and allows you to claim up to two times your full cover amount; SIC 3X covers 174 conditions with payouts between 5% and 100% and allows claims up to three times your full cover amount.
In 2024, Vitality paid out £44.4 million in Serious Illness Cover claims. One in five claims Vitality paid in 2024 would not have been covered by a typical core critical illness plan. That statistic matters for Brize Norton personnel. A standard critical illness policy would have left one in five of those claimants with nothing.
Vitality’s severity-based payment structure enables pay outs to clients for far less severe conditions, with the opportunity for multiple claims for the same or separate conditions as the severity of the condition worsens. This is particularly relevant for RAF personnel, many of whom face ongoing health challenges following high-intensity physical work, operational stress, or injuries sustained during service careers.
AFPS15 provides no critical illness or serious illness cover. Life and personal accident insurance cover complements the Armed Forces pension and compensation provisions already available to service personnel and is optional. It is for the individual to decide whether they wish to enhance their protection by taking out life or personal accident insurance cover. Service personnel, particularly those with dependants, should regularly consider their financial position as to whether the insurance cover they have is sufficient to meet their personal circumstances, especially when changes have occurred, for example getting married or having children.
To discuss your Serious Illness Cover options with a specialist, speak to the team at our Vitality coach page, where you can get a clear picture of which tier is appropriate for your rank, pay, and family situation.
VitalityLife Life Cover
Separate from Serious Illness Cover, VitalityLife Life Cover can sit alongside your AFPS15 death in service benefit to extend and strengthen the protection your family receives. The military does not provide personal life insurance, but serving personnel do have some financial protection called death in service through the Armed Forces Pension Scheme. For most people, this is unlikely to be enough on its own to clear a mortgage or replace lost income, which is why many choose to arrange their own cover on top of it.
A personal life insurance policy remains in place when you leave the service. Your AFPS15 death in service benefit does not. Death in service normally stops if you leave the forces, either to retire or to move into a civilian career. That means your loved ones could lose this protection just when you are taking on a mortgage or starting a family. Arranging your own policy while serving locks in your health rating at a younger, healthier point in life and ensures continuity of cover through the transition.
The Vitality Programme
Every VitalityLife policy comes with access to the Vitality Programme, a rewards scheme designed to recognise and benefit healthy behaviour. For RAF Brize Norton personnel, whose working lives already involve physical fitness and disciplined health habits, the programme is a genuine asset rather than an afterthought.
Vitality Rewards is a scheme that gives members of qualifying Vitality Health and Life Insurance plans discounts and freebies when they stay active and look after their health. You earn points for things like health checks, exercise, steps and preventive screenings, which build up your Vitality status from Bronze through to Silver, Gold and Platinum.
As your status improves, you unlock bigger rewards such as discounted David Lloyd and Nuffield gym memberships, cheaper spa breaks, free Caffè Nero drinks, cinema tickets, cashback on healthy food and reduced monthly payments on devices such as an Apple Watch. For families in Carterton and Witney, these are meaningful, real-world savings that accumulate throughout the year. Members can receive up to 50% off monthly memberships at Nuffield Health Fitness and Wellbeing Centres, PureGym gyms or Virgin Active gyms.
Find out more about maximising your rewards at our Vitality coach page, where our advisers can walk you through how to get the most from the programme alongside your cover.
Personal Accident Cover
Personal accident cover pays a cash benefit directly to you if you suffer a qualifying injury, whether on duty, off duty, on exercise, deployed overseas, or playing sport. It is distinct from life insurance, which pays on death, and distinct from serious illness cover, which pays on diagnosis of a medical condition.
Absolute Military’s Personal Accident Cover starts from £3.79 per month per unit and was rated in the 96th percentile for lowest price in Fairer Finance’s independent 2026 assessment.7 It covers the injuries that matter in military life: conflict wounds, cold injuries, fractures, dislocations, ligament tears and more.
Holding a personal accident policy has no impact on any AFCS entitlement. The two are entirely independent: you can hold both without one affecting the other. This is an important point that is frequently misunderstood. Taking out personal accident cover does not reduce your Armed Forces Compensation Scheme entitlement in any way.
Kit Insurance for Brize Norton Personnel
Personnel at RAF Brize Norton hold kit on personal charge. Standard home contents policies do not cover military-issued kit, kit held in service accommodation, or equipment taken on operations or exercises. Absolute Military’s Kit Insurance, arranged via Hamilton (rated number one for kit insurance by Fairer Finance), is built specifically for this environment.
Whether you live in single living accommodation on camp or in service family accommodation in Carterton, your kit needs dedicated protection. Passengers travelling through RAF Brize Norton are advised to insure their baggage against loss or damage. The cost of insurance incurred by passengers is not recoverable from public funds. The same principle applies more broadly: the MoD will not compensate you for kit lost or damaged through circumstances that fall outside its specific liability rules.
Mortgages
Forces Help to Buy and the practicalities of a posting cycle make mortgage planning more complex for RAF Brize Norton personnel than for civilian buyers. A free mortgage advice service is available at the Support Building at RAF Brize Norton. Absolute Military works with John Greasby, a whole-of-market mortgage adviser with specific experience in Forces Help to Buy applications and the challenges of buying while posted. Speak to us for an introduction.
For the latest rates, lender criteria, and market commentary relevant to serving personnel, see our October 2026 Market Review.
The Carterton and Oxfordshire Context
Brize Norton’s connection to the RAF’s largest military airbase gives Carterton a significant proportion of service families: mobile, often young, frequently on posting rotations. Military families at Brize Norton follow posting cycles of typically two to three years. That mobility makes getting financial planning right early in a posting genuinely important. A policy arranged on arrival provides protection for the whole tour. A policy left until departure may never be arranged at all.
RAF Brize Norton is located in Oxfordshire, approximately 75 miles west-northwest of London, near the village of Brize Norton and the towns of Carterton and Witney. Families registering with local GPs in Carterton and planning their financial affairs should treat protection cover as part of the settling-in process, alongside school registration and healthcare.
Frequently Asked Questions
Does AFPS15 cover me if I am diagnosed with cancer or suffer a heart attack while serving at RAF Brize Norton?
No. If you die in service, your spouse or partner will receive an immediate pension paid for life and a tax-free lump sum. But AFPS15 makes no payment in response to a serious illness diagnosis alone. If you are diagnosed with cancer, suffer a heart attack, or have a stroke while serving, you continue serving or are medically discharged, but there is no lump sum from AFPS15 to cover your recovery costs. Serious Illness Cover fills this gap directly.
Can I get income protection insurance as a regular serving RAF personnel member?
Income Protection plans are only available for part-time Reservists who are not about to go on a tour of duty to an active theatre of operations or conflict, do not take part in any high-risk roles such as bomb disposal or aviation. Regular serving personnel cannot purchase standard income protection. This makes Serious Illness Cover the most important personal protection product available to you.
Does taking out personal accident cover affect my Armed Forces Compensation Scheme entitlement?
Holding a personal accident policy has no impact on any AFCS entitlement. The two are entirely independent, and you can hold both without one affecting the other. Your AFCS claim is assessed on its own merits regardless of any personal insurance you hold.
What happens to my AFPS15 death in service benefit when I leave the RAF?
Death in service normally stops if you leave the forces, either to retire or to move into a civilian career. That means your loved ones could lose this protection just when you are taking on a mortgage or starting a family. A personal life insurance policy arranged while serving continues after discharge, which is why it is important to put cover in place before you leave rather than after.
Why is Vitality Serious Illness Cover particularly suitable for RAF personnel?
In 2024, one in five claims Vitality paid would not have been covered by a typical core critical illness plan. If you make a claim and receive a partial pay out, for example 25% of your cover, the rest of your cover stays in place should you need to claim again. The severity-based, multiple-claim structure means that personnel with complex or ongoing health conditions are more likely to receive a meaningful pay out than they would be under a standard critical illness policy that requires a condition to reach a fixed severity threshold before paying anything at all.
Reviewed by Paul O’Mahoney
All the information in this article was accurate at the time of publication. This may be subject to change.
Sources
- RAF Brize Norton. Royal Air Force (MOD), accessed 23 October 2026
- Armed Forces Pension Scheme 15. MOD Discover My Benefits, accessed 23 October 2026
- A timely summary of the key benefits of AFPS15. Forces Pension Society, accessed 23 October 2026
- Changes to the Armed Forces Pension Schemes. Royal Air Force (MOD), accessed 23 October 2026
- Life and Personal Accident Insurance and AFPS Declaration Forms. Royal Air Force (MOD), accessed 23 October 2026
- Vitality Serious Illness Cover Review 2026. Reassured, accessed 23 October 2026
- Military Personal Accident Insurance. Absolute Military, accessed 23 October 2026
- Occupation and Armed Forces. Legal & General, accessed 23 October 2026
- RAF Brize Norton Station Handbook. Royal Air Force (MOD), accessed 23 October 2026
- Military Life Insurance. Trinity Financial, accessed 23 October 2026
- VitalityLife Showcase. Protection Guru, accessed 23 October 2026
- Vitality Insurance Rewards Guide. iam INSURED, accessed 23 October 2026